Sometimes the most valuable asset in a business is a permit. In this deal, the permits shaped the whole structure.
Here’s how a buyer from outside the industry acquired an established car service without missing a day of revenue.
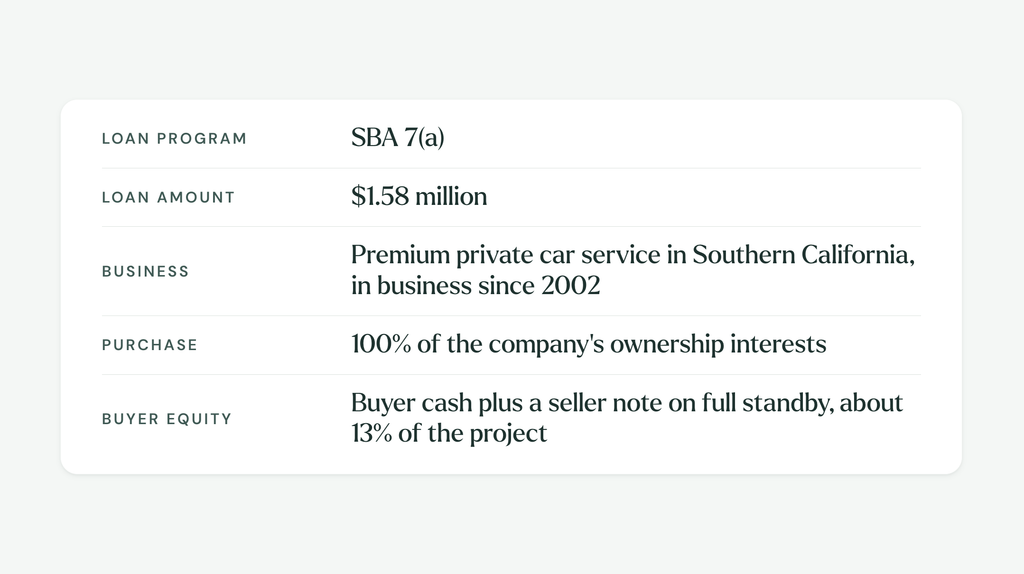
The business
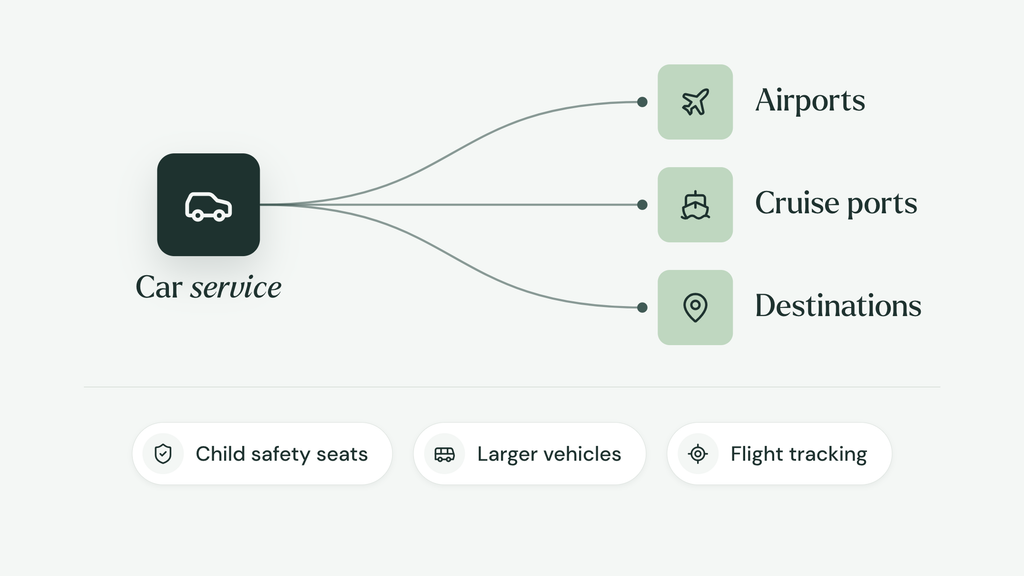
The company runs a reservation-only private car service. Most rides are airport transfers, along with trips to cruise ports, major tourist destinations, and hourly charters.
Its customers are mostly families and groups. The fleet includes SUVs, vans, and larger passenger vehicles, and every ride comes with free child safety seats, flight tracking, and baggage claim pickup. That is a service rideshare apps don’t really offer, which is why the company has held its ground for more than 20 years.
The company was owned by a father and son. The father was ready to retire, and the son wanted to pursue a different career. They decided to sell.
The buyer
The buyer is an aerospace engineer and program manager who has led large engineering teams and multimillion-dollar programs. He also built a vending business from scratch, so he has run a business of his own before.
What he didn’t have was experience running a transportation company. His plan was to start with the systems: payroll, scheduling, and driver training. Then he would grow through paid marketing, a modest price increase, and new partnerships the sellers had never pursued.
The hard part: the permits
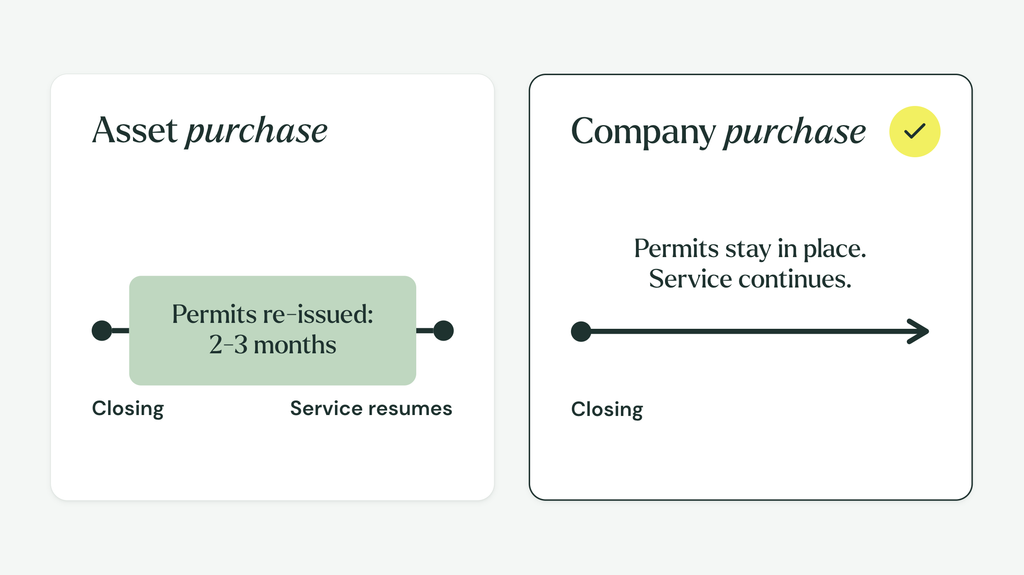
The deal started as an asset purchase. That’s the usual approach, because the buyer gets the vehicles and the customer list without taking on the old company.
In this business, though, the license to operate sits with the company. Its state transportation certificate and airport permits are what let its cars pick up passengers at the terminal. In an asset purchase, every vehicle and driver would have to move onto new permits under the buyer. That process was expected to take two to three months.
For a business that earns most of its revenue from airport runs, two or three months without permits could have done real damage, right when the new owner was taking over.
How it came together
- Buy the company, not just the cars. The buyer switched to purchasing 100% of the company’s ownership interests. The company and its permits stayed in place, and only the owner changed. Before closing, the buyer still had to confirm with regulators that operations would continue without interruption.
- Clean up the company before closing. Buying a company means buying its history, so the sellers agreed to clear any liabilities from the company before the sale.
- The buyer covered the valuation gap. An independent valuation came in slightly below the purchase price. Under SBA rules, that difference had to come from the buyer’s own cash, so he added it to his down payment.
- The seller stayed invested. The sellers carried a note on full standby, with no payments until the SBA loan is repaid. It counted toward the buyer’s required equity.
- A hands-on transition. The sellers committed to a month of training and 90 days of phone support. One seller stayed on as a driver until a replacement was hired, and all the existing drivers are staying.
The structure
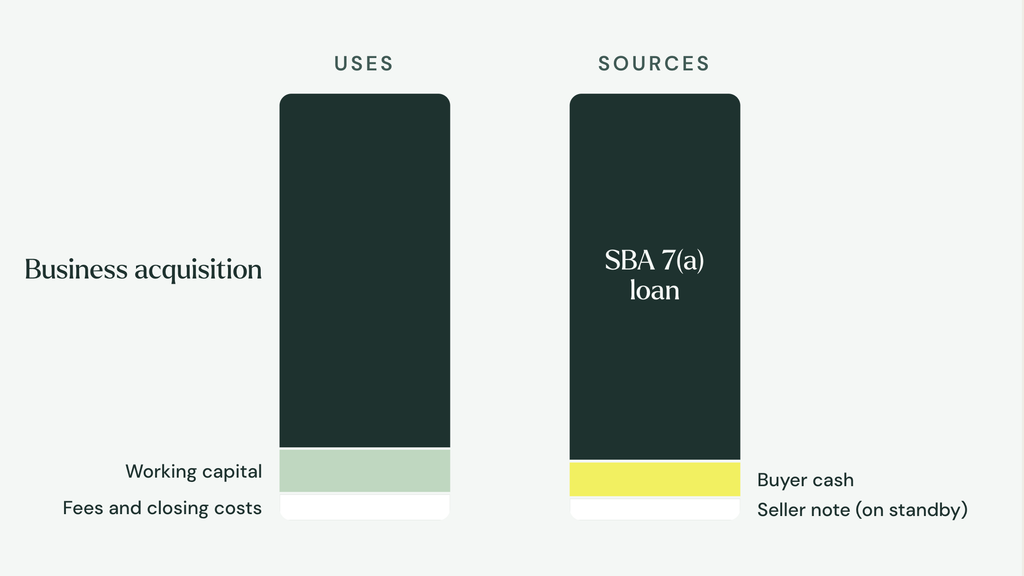
One SBA 7(a) loan for $1.58 million covered about 87% of the $1.81 million project. The buyer’s cash and the seller note covered the rest.
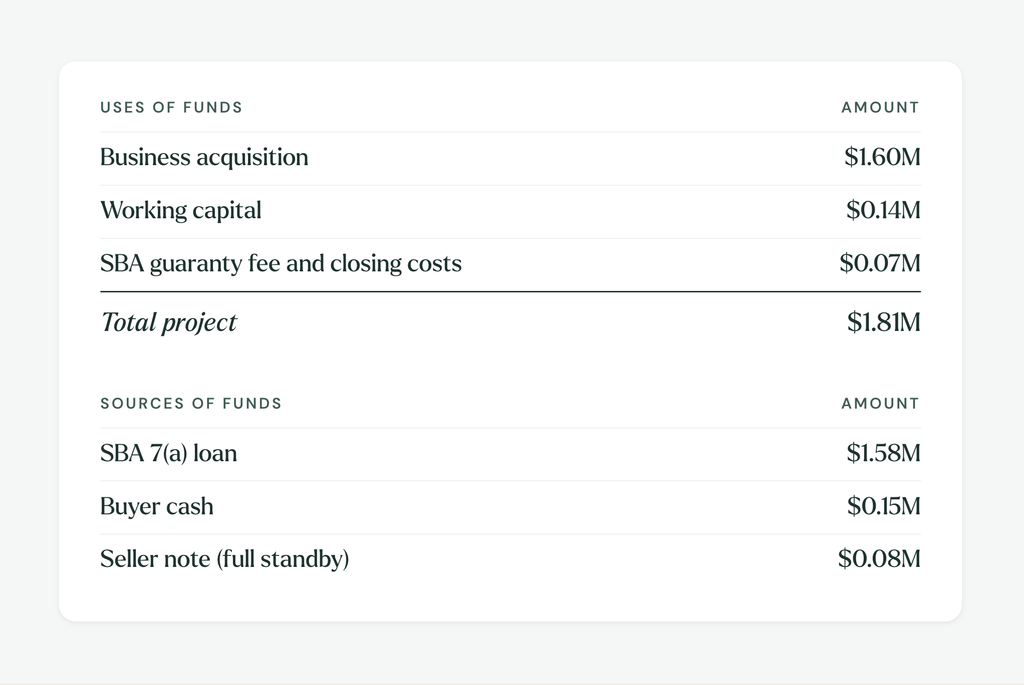
No cash or receivables came with the sale, so the working capital gives the new owner a cushion of about three months. It covers payroll, insurance, and unplanned vehicle repairs while the business builds its own cash. The loan has a 10-year term and is secured by all business assets. Our bank partner made the credit decision and funded the loan.
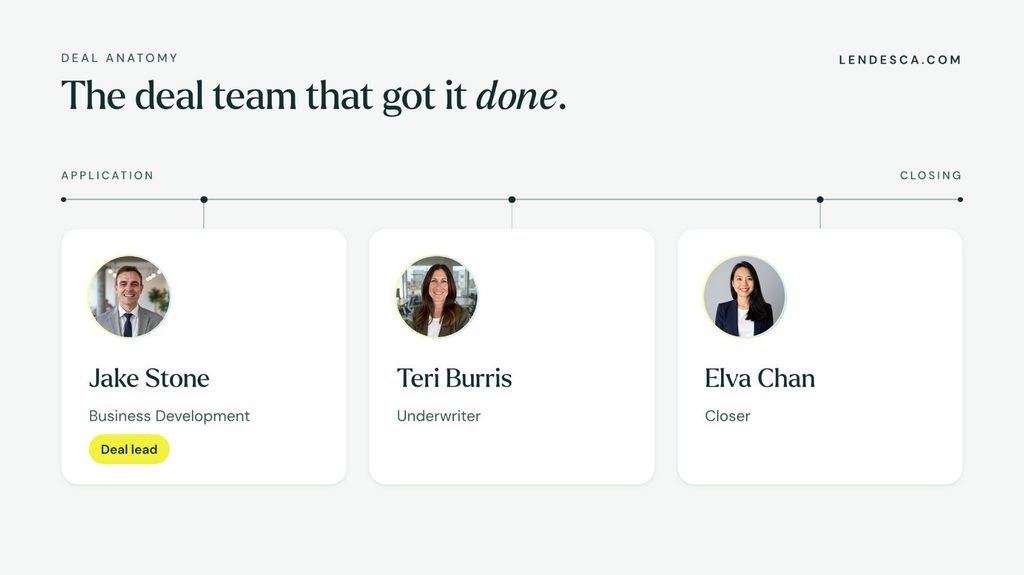
Lendesca handled everything in between. We built the file, structured the request, and managed it from the first conversation through closing, with one team on the deal the whole way.
What to watch for in your own clients
Deals like this one show up in CPA practices, M&A advisory firms, and bank pipelines more often than people expect. These are the signals worth paying attention to:
- A client wants to buy a business in an industry they haven’t worked in
- The business depends on licenses or permits that are slow to transfer
- A deal was set up as an asset purchase without weighing a company purchase
- A valuation came in under the asking price
- The sellers are retiring and willing to carry a note and help with the transition
- The business runs on a small team and systems a new owner can learn
If two or more of these sound familiar, it’s worth a conversation.
Two ways to get started
For referral partners
Have a client looking to buy a business? Send them our way. We’ll handle it from the first conversation to closing and keep you updated on deal status the whole way.
Become a Lendesca Referral Partner
For business owners
Thinking about buying a business? Let’s get your SBA loan structured the right way and funded. One team works with you from application to funding.
This case study describes a single transaction for illustrative purposes. Some details have been generalized to protect the borrower’s privacy. Lendesca is not a lender. Credit decisions are made by, and loans are funded by, our bank partner. SBA loans are subject to SBA eligibility requirements and bank credit review. Equity requirements, valuation standards, deal structure, and terms depend on each transaction and on current SBA rules.